Solar Incentives in Owego, NY: What Applies in 2026
Owego keeps a state credit, a NYSERDA price reduction and a property tax exemption four separate bodies can each cancel. The federal credit is gone, which changes how a lease should be read.
On this page 9 sections
- 01Start with what is gone
- 02The New York State credit, and the ten-year line it draws
- 03NY-Sun and Affordable Solar have closed for homes
- 04RPTL 487 means four separate checks in Owego
- 05Design review: ask the village rather than assume
- 06Flood plain siting decides where a battery may go
- 07NYSEG and the charge that offsets the incentives
- 08One thing to verify before any of this applies
- 09Frequently Asked Questions
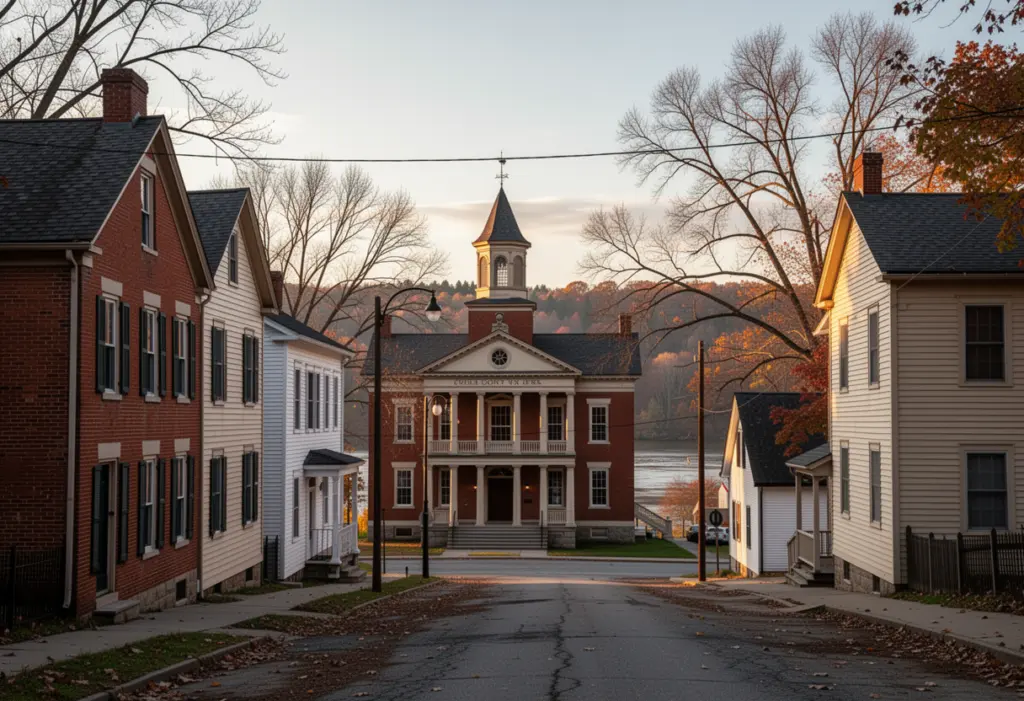
Owego is an incorporated village and the county seat of Tioga County, sitting on the Susquehanna inside the surrounding Town of Owego. ZIP code 13827. What is available to a homeowner here in 2026 is a shorter list than it was a year ago, and the shape of the offer you are shown has changed with it.
Start with what is gone
The 30% federal residential credit no longer exists for a buyer. Section 25D was terminated for expenditures made after 31 December 2025, and an expenditure is treated as made when the original installation is completed. Check that line before anything else on a proposal, because every figure derived below it depends on it.
What survives federally is the business-side credit, claimed by the company that owns a leased or power purchase agreement system. That is why third-party offers still price in an incentive a buying homeowner never sees, and it is why lease and PPA paperwork deserves a much closer reading in 2026 than it did in 2024.
The New York State credit, and the ten-year line it draws
New York’s solar energy system equipment credit is 25% of qualified expenditure, capped at $5,000, claimed on Form IT-255. Unlike the federal one it does reach third-party arrangements, but only on terms most sales conversations skip:
- It covers a purchase, a lease of ten years or more, or a power purchase agreement of ten years or more. The ten-year minimum applies to the lease as well as the agreement, so a five- or seven-year lease qualifies for nothing.
- The 25% does not work the same way on the two. On a power purchase agreement the credit is 25% of that year’s payments. On a lease it is the payments you actually made that year, capped by 25% of the total contracted payments or $5,000, whichever is less.
- On either, no credit is allowed after the fifteenth year of a longer agreement, even where the $5,000 has not been used up, and that $5,000 is a lifetime ceiling for the agreement rather than an annual figure.
- The system must serve your principal residence in New York, and the credit is limited by your actual state tax liability. It is not refundable, though unused credit carries forward for up to five years.
Read those against any lease or PPA put in front of you before comparing monthly figures. A twenty-year agreement and a seven-year one are not two versions of the same product where this credit is concerned.
NY-Sun and Affordable Solar have closed for homes
NY-Sun was applied by your contractor as a reduction in the quoted price rather than claimed by you, and the per-watt amount stepped down as each regional capacity block filled. The last standard upstate residential block (Block 14, $0.15/W, NYSEG, RG&E and National Grid territories) closed on 17 December 2025. Affordable Solar, NYSERDA’s higher per-watt block for lower-income households, was also applied by the contractor; the upstate one paid $0.80 per watt from 18 December 2025 to 9 March 2026. As of September 2026 NYSERDA has no open NY-Sun block for homes in any utility territory; check NYSERDA’s NY-Sun dashboard for a new one. A 2026 quote that still shows either line should name the open block it relies on.
RPTL 487 means four separate checks in Owego
RPTL 487 exempts the added value of a solar system from real property tax for 15 years, but only where the taxing bodies have not opted out, and that right belongs separately to each. For a village address here that is the Village of Owego, the Town of Owego, Tioga County and your school district. Ask about all four by name rather than accepting a general assurance, file form RP-487 with the assessor by the taxable status date, and note that section 487 requires construction before 1 January 2030. The state sales tax exemption on residential solar equipment applies as well, with localities separately electing whether to exempt their local share.
Design review: ask the village rather than assume
Owego’s older centre is a nineteenth-century streetscape, and communities protect streetscapes like it in more than one way. The distinction that matters to a homeowner is this: a local landmark or historic district ordinance can put design review ahead of a building permit and restrict street-visible placement, while a state or national register listing, if a property or a district happens to carry one, is a form of recognition and does not by itself impose design review on private work at a private house. The two are frequently confused, including by installers.
So ask the Village of Owego directly whether local design review applies to your address, and treat any answer that comes from a sales representative as provisional. If review does apply, design for approval rather than arguing after refusal: a rear or secondary roof plane out of sight of the public way, all-black modules with black frames, flush mounting that follows the roof plane, and conduit run internally or painted where it must be exposed. Ask when the board meets, because a missed monthly deadline is four weeks of delay and can push a project across a programme year.
Flood plain siting decides where a battery may go
The village stands on the Susquehanna, and the low ground carries a mapped flood zone. Its practical effect is on mounting height: an elevation is specified and everything electrical has to clear it, so the inverter and the disconnects go wherever that can be achieved and storage almost never goes downstairs. Establish whether the zone covers your parcel before you are shown a design, rather than afterwards.
NYSEG and the charge that offsets the incentives
Set against the incentives is a monthly charge. Any system interconnected on or after 1 January 2022 pays the Customer Benefit Contribution, sized on the array’s DC rating, and NYSEG’s residential figure for 2026 is $1.19 per kW-month:
- A 5 kW system: $5.95 a month, about $71 a year.
- An 8 kW system: $9.52 a month, about $114 a year.
The measure is capacity, not output, and the rate is set afresh every year. Against it, Phase One net metering pays the full retail rate for exported kilowatt-hours and keeps that structure for two decades. Community solar subscribers pay no Customer Benefit Contribution at all, since a community project sits in front of the meter rather than behind it, and that matters at any address where a roof, a design restriction or a flood zone rules a rooftop system out.
One thing to verify before any of this applies
The tax provisions above are statewide, but the net metering and Customer Benefit Contribution figures are utility-specific, so confirm the utility from the name printed on your own bill. Most of Tioga County is NYSEG, though territory boundaries do not track county or village lines. The exception worth knowing about is a municipal electric utility: where a New York village owns its system, its customers fall outside Public Service Commission jurisdiction, and state net metering, the Customer Benefit Contribution and the standardised interconnection process do not apply to them at all. Terms in that case are the utility’s own and must be asked for directly.
Incentive programmes move. The NY-Sun megawatt blocks for homes have all closed, the contribution is recalculated annually, and section 487 has an end date. Check the current position with NYSERDA and the New York Department of Taxation and Finance before you commit.
Frequently Asked Questions
Is there still a federal solar tax credit in Owego in 2026?
Not for a homeowner buying a system. Section 25D was terminated for expenditures made after 31 December 2025, and an expenditure counts as made when the original installation is completed. What survives is the business-side credit claimed by the owner of a leased or PPA system.
Does a solar lease qualify for the New York State credit?
Only a lease of ten years or more, and the same minimum applies to a power purchase agreement. On a lease the credit is the payments made that year, capped by 25% of total contracted payments or $5,000, and no credit is allowed after the fifteenth year.
Whose property tax exemption do I have to check in Owego?
For a village address, four bodies separately: the Village of Owego, the Town of Owego, Tioga County and your school district. Each may opt out of RPTL 487 on its own, so ask about them by name rather than accepting a general assurance.
Does a historic designation block solar in Owego?
That depends on which kind applies, so ask the village rather than assume. A local landmark or historic district ordinance can impose design review ahead of a permit; register listing alone does not impose review on private work at a private house.
This article is general information, not tax, legal or financial advice. Incentive amounts, eligibility rules and deadlines change and depend on your utility, your tax situation and your property. Confirm current terms with NYSERDA, your utility and a qualified tax professional before making a decision.
NY Solar Incentives
Independent New York solar research. We summarise NYSERDA, NY-Sun and federal programme rules from published sources and state plainly when a figure is an estimate. We are not a government agency and do not sell equipment.
Run the arithmetic on your own system
Check the dated program table and your arrangement before counting an incentive. Standard residential NY-Sun blocks are closed; Long Island Affordable Solar has a conditional income-verification route. The NY credit depends on qualified costs and tax liability, while the NYC abatement reduces future property-tax bills. The estimator keeps those timings separate.