Solar Incentives in Cortland County, NY
Cortland County is valleys between wooded hills in NYSEG territory. Two questions settle most projects before a design exists.
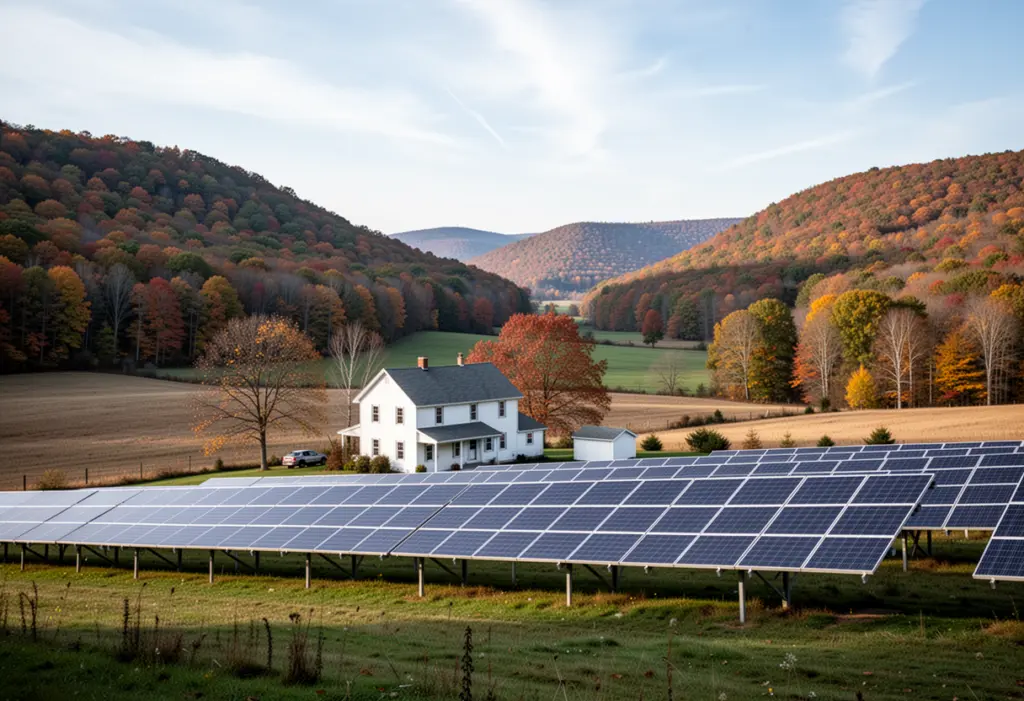
Cortland County sits between the Finger Lakes and the Southern Tier — Cortland, Homer, Marathon, McGraw, Truxton. ZIP codes here begin 130 and 138. It is valley and hill farming country, and two questions settle most projects before a design exists.
Question one: the southern horizon
Valleys running between wooded hills mean the sun arrives late and leaves early on a great many properties, and the low December sun is what makes it decisive.
Insist on an on-site shading assessment, not a satellite estimate, and ask what the model assumes about December and January rather than only the annual total. In this terrain two installers can differ substantially on the same roof.
Where the roof will not work, most properties here have land for a ground mount, which lets the array go where the sun is instead of where the roof happens to face, removes the roof-age question and allows ground-level maintenance and snow clearing.
Question two: hosting capacity
Cortland is NYSEG territory, and its rural feeders are where interconnection applications hit limits — an application can come back requiring a study or a distribution upgrade before a system is accepted.
Ask whether hosting capacity was checked for your circuit before designing, and settle two things in writing before signing: when the application will be filed — before installation, so a surprise arrives before your roof has been drilled — and what happens to your deposit if a study or upgrade is required.
The Customer Benefit Contribution is $1.19 per kW-month of DC system size for 2026: about $5.95 a month on a 5 kW system and $9.52 on 8 kW. Billed on capacity regardless of production and recalculated annually.
Permits
The City of Cortland and the surrounding towns — Cortlandville, Homer, Virgil, Preble and the rest — each run their own building departments with their own turnarounds. The utility step is identical everywhere; the municipal step is not. Ask which authority covers your address and what it is currently running at.
Farmland
A project to offset a farm’s own consumption sits on the business side of the tax code, where the investment tax credit and depreciation did not follow the residential credit into repeal at the end of 2025 — a live question for your accountant with your own figures. Get interval data from the utility rather than bill totals, and ask any proposal to separate energy savings from demand savings.
Leasing ground to a developer is a separate decades-long decision whose terms on decommissioning security, rent escalation, access routes, drainage and tile, the option period and agricultural assessment matter more than the headline rent. Use your own attorney.
Roofs, snow and sizing
Housing here is old, so roof age is frequently the gate: under roughly ten years of shingle life left means re-roof first. Snow load is real and racking must be specified for it — ask what snow assumption is in the production estimate.
Get twelve months of usage before accepting a design; electric hot water and supplementary electric heat are both common and push winter consumption above what a template assumes.
2026 incentives
The 30% federal residential credit is gone — section 25D was terminated for expenditures made after 31 December 2025, with an expenditure treated as made when the original installation is completed.
Still available: New York’s 25% credit capped at $5,000 on Form IT-255, non-refundable but carried forward five years and reaching leases and PPAs of ten years or more as well as purchases; the state sales tax exemption; and RPTL 487’s 15-year property tax exemption, claimed on form RP-487 filed with your assessor by the taxable status date, where your city, town or village, the county and your school district have not opted out, so check each of them. NY-Sun and its Affordable Solar track are not: as of September 2026 NYSERDA has no open NY-Sun block for homes in any utility territory; check NYSERDA’s NY-Sun dashboard for a new one.
Where the horizon rules a roof out, community solar operates in NYSEG territory, needs no roof or up-front cost, and its subscribers pay no Customer Benefit Contribution at all.
Frequently Asked Questions
Is Cortland County's valley position a problem for solar?
It can be. Valleys between wooded hills mean the sun arrives late and leaves early on many properties, and the low December sun makes that decisive. An on-site shading assessment is essential, and a ground mount is often the answer.
Should I ask about hosting capacity in Cortland County?
Yes. NYSEG's rural feeders are where applications come back needing a study or a distribution upgrade. Ask whether it was checked for your circuit before design, and settle what happens to your deposit if an upgrade is required.
Who issues a solar permit in Cortland County?
The City of Cortland or your town — Cortlandville, Homer, Virgil, Preble and the rest each run their own building department with their own turnaround. The NYSEG step is identical across all of them.
What does NYSEG charge a Cortland County solar customer?
The Customer Benefit Contribution at $1.19 per kW-month of DC system size for 2026 — about $5.95 a month on a 5 kW system and $9.52 on 8 kW.
This article is general information, not tax, legal or financial advice. Incentive amounts, eligibility rules and deadlines change and depend on your utility, your tax situation and your property. Confirm current terms with NYSERDA, your utility and a qualified tax professional before making a decision.
NY Solar Incentives
Independent New York solar research. We summarise NYSERDA, NY-Sun and federal programme rules from published sources and state plainly when a figure is an estimate. We are not a government agency and do not sell equipment.
Run the arithmetic on your own system
Check the dated program table and your arrangement before counting an incentive. Standard residential NY-Sun blocks are closed; Long Island Affordable Solar has a conditional income-verification route. The NY credit depends on qualified costs and tax liability, while the NYC abatement reduces future property-tax bills. The estimator keeps those timings separate.