Solar for a Co-op Building: Getting Board Approval
In a co-op you are not asserting a right, you are making a case. Here is what the board actually needs to see.
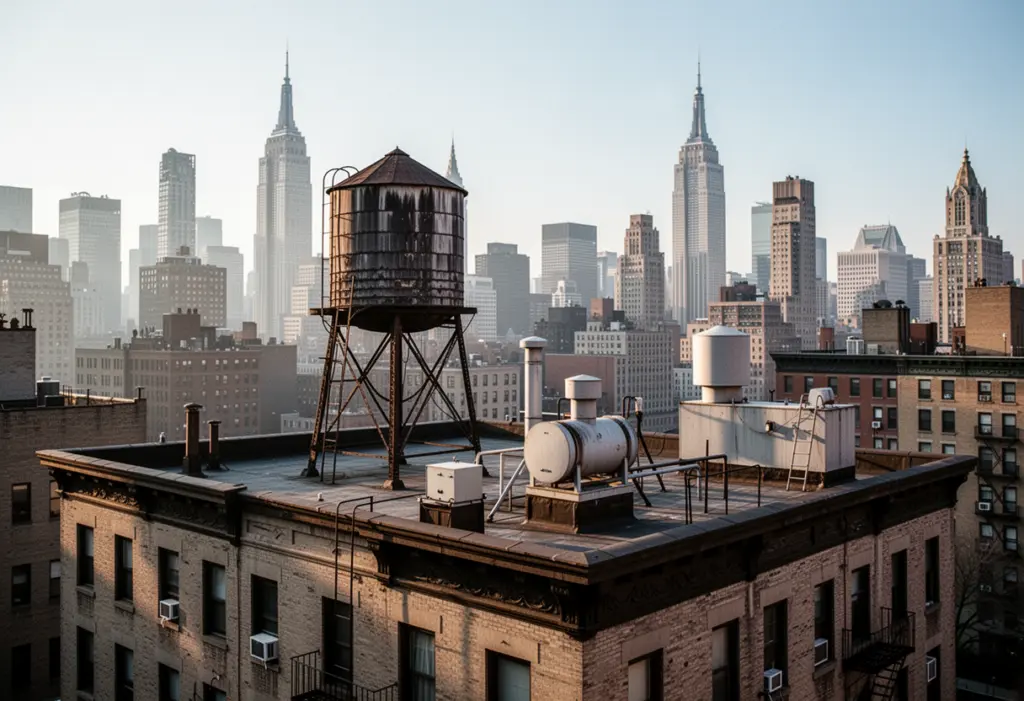
New York law limits how far a homeowners association can obstruct solar on property the homeowner owns. In a co-op, that protection does not do the work people hope, and the reason is structural: you do not own the roof. A co-op shareholder owns shares and a proprietary lease. The roof is common property, and putting anything on it is a board decision.
So this is not a rights conversation. It is a proposal, and it succeeds or fails on how it is made.
Start with the right project
A co-op solar project is almost never one shareholder’s array. It is a building system serving the building’s own consumption — the boiler, elevators, hallway and stairwell lighting, laundry, the compactor — which is billed to the corporation and paid out of maintenance.
That reframing is what makes the proposal work. It is not a request for personal benefit from common property; it is a proposal to reduce a shared operating cost.
What a board needs to see
- Twelve months of the corporation’s own electricity usage, from the actual bills. This is the foundation and it is the thing an outside installer cannot obtain for you.
- A roof condition report. Boards think in capital plans. If the roof is due for replacement in four years, the sensible proposal is to sequence solar with that work, and saying so first establishes that you understand the building rather than just the panels.
- A structural assessment. On an older building this is not optional and the board will ask.
- Effect on the roof warranty. Penetrations can affect a membrane warranty. Ballasted mounting, common on flat New York roofs, may avoid penetrations entirely — this is a specific question with a specific answer.
- What is displaced from the roof. Tank, cooling equipment, bulkhead access, tenant amenity space. Boards care about this more than about kilowatts.
- Who owns and maintains the system, and what happens at end of life.
- The financial case — cost, incentive, projected saving to the corporation, and an honest payback range rather than a single number.
The incentive position for a corporation
This is where a co-op differs sharply from a house, and it needs the corporation’s accountant rather than an installer.
New York’s 25% residential credit on Form IT-255 is for an individual’s principal residence — it is not the provision that applies to a co-op corporation’s building system. The relevant treatment depends on how the corporation is taxed and how any benefit passes through to shareholders. The federal residential credit under section 25D ended for expenditures made after 31 December 2025 in any event, while the business-side investment tax credit is a separate provision.
Do not let a proposal assert a tax benefit the corporation has not confirmed with its own accountant. It is the most common weakness in co-op solar proposals and the fastest way for a board to reject one.
NY-Sun does have non-residential incentives, paid through the contractor, and those are worth establishing early.
Practical route through the board
- Talk to the managing agent before the board. They know the capital plan, the roof history and how proposals get put on an agenda.
- Find the ally. Boards approve proposals with an internal champion far more often than ones arriving from outside.
- Bring one proposal, not three quotes. A board is not going to run a procurement exercise; it will approve or reject a recommendation.
- Answer the objection before it is raised. Roof warranty, structure, appearance from the street, and what happens if the installer disappears.
If the roof is not available
Community solar needs no roof and no board. A shareholder can subscribe individually for their own apartment’s usage, and the credit lands on their own utility account. It requires nothing of the building and no approval from anyone.
For many co-op residents that is the realistic answer, and it is worth knowing before a year is spent on a proposal that was never going to clear a capital plan.
Frequently Asked Questions
Can a co-op board refuse solar panels in New York?
Yes. A co-op shareholder owns shares and a proprietary lease, not the roof, which is common property. The protection that stops a homeowners association obstructing solar applies to property the homeowner owns, so in a co-op it is a board decision rather than a right.
What should a co-op solar proposal contain?
Twelve months of the corporation's own electricity usage, a roof condition report, a structural assessment, the effect on the roof warranty, what the array displaces from the roof, who owns and maintains the system, and an honest financial case with a payback range.
Can a co-op claim the New York solar tax credit?
The Form IT-255 credit is for an individual's principal residence, not a corporation's building system. The applicable treatment depends on how the corporation is taxed and how benefits pass through, so it needs the corporation's own accountant rather than an installer's assertion.
What can a co-op resident do if the board says no?
Subscribe to community solar individually. It needs no roof and no board approval, and the credit lands on the resident's own utility account rather than the building's.
This article is general information, not tax, legal or financial advice. Incentive amounts, eligibility rules and deadlines change and depend on your utility, your tax situation and your property. Confirm current terms with NYSERDA, your utility and a qualified tax professional before making a decision.
NY Solar Incentives
Independent New York solar research. We summarise NYSERDA, NY-Sun and federal programme rules from published sources and state plainly when a figure is an estimate. We are not a government agency and do not sell equipment.
Run the arithmetic on your own system
Check the dated program table and your arrangement before counting an incentive. Standard residential NY-Sun blocks are closed; Long Island Affordable Solar has a conditional income-verification route. The NY credit depends on qualified costs and tax liability, while the NYC abatement reduces future property-tax bills. The estimator keeps those timings separate.